Air Miles Credit Cards in Singapore Compared
For everyday spending UOB PRVI Miles earns the most — 1.4 miles per S$1 locally and 2.4 overseas — but costs S$261.60 a year. HSBC TravelOne matches 2.4 overseas for a lower S$196.20 fee and free mile transfers.
An air miles card turns everyday spending into frequent-flyer miles, but the cards differ more in the small print than in the headline “miles per dollar”. The rate you earn locally, the annual fee, how your points convert to an airline, and whether they expire all change the real value. Here is how Singapore’s main general-spending miles cards compare, as of October 2026, with every figure taken from each bank’s own card page.
How miles cards actually work
Miles are quoted as mpd — miles per dollar. A card that earns “1.4 mpd” gives 1.4 miles for every S$1 charged. Two numbers matter, and most marketing shouts only the second:
- Local rate: what you earn on Singapore-dollar spend. In a small city where most daily spending is in SGD — groceries, transport, dining, bills — this rate drives the bulk of your miles.
- Overseas rate: what you earn on foreign-currency spend. It is usually higher, but it only applies when you travel or shop on overseas sites, and it comes with a foreign-currency fee (commonly around 3.25%, confirm the exact figure on each bank’s page) that eats into the extra miles.
Most cards pay miles indirectly: you earn the bank’s own points (UNI$, DBS Points, Reward points, 360 Rewards Points, 90°N Miles), then transfer them to an airline programme such as KrisFlyer. That transfer step is where fees and expiry dates hide.
The winner: UOB PRVI Miles
On published earn rates alone, UOB PRVI Miles leads the general-spending pack: 1.4 miles per S$1 locally (UNI$3.5 per S$5) and 2.4 miles per S$1 on general overseas spend (UNI$6 per S$5) — the highest local rate of any mainstream miles card. It adds 3 miles per S$1 on spend in Malaysia, Indonesia, Thailand and Vietnam, and up to 6 miles per S$1 on major airlines and hotels booked through Agoda, Expedia and UOB Travel links.
The trade-off is the fee. The principal card costs S$261.60 a year (first year waived), about S$65 more than its rivals, and only the American Express variant offers a spend-based waiver — at S$50,000 of anniversary-year spend. Miles are paid as UNI$ and convert at UNI$1 = 2 miles, with a conversion fee each time you transfer.
Runner-up: HSBC TravelOne
HSBC TravelOne matches the winner where it counts for travellers — up to 2.4 miles per S$1 on foreign-currency spend — for a lower S$196.20 annual fee. Its local rate is lower at 1.2 miles per S$1, but two things set it apart: it charges no redemption fee when you convert to airline miles or hotel points (most rivals charge around S$25-S$27 a transfer), and it includes 4 complimentary airport-lounge visits a year to over 1,300 lounges for the primary cardholder. From the second year, paying the fee returns up to 12,000 miles (as 30,000 Reward points). The catch is eligibility: the headline income requirement is S$65,000 unless you are a Singaporean or PR who holds at least S$50,000 with HSBC, in which case it drops to S$30,000.
The whole market, side by side
The other mainstream general-spending cards cluster around the same S$196.20 fee but differ on rates, bonuses and expiry:
| Card | Local | Overseas | Standout | Annual fee |
|---|---|---|---|---|
| UOB PRVI Miles | 1.4 mpd | 2.4 mpd | 3 mpd in MY/ID/TH/VN; up to 6 mpd via Agoda/Expedia/UOB Travel | S$261.60 (1st yr waived) |
| HSBC TravelOne | 1.2 mpd | 2.4 mpd | Free mile transfers; 4 lounge visits | S$196.20 (1st yr waived) |
| DBS Altitude | 1.3 mpd | 2.2 mpd | DBS Points never expire | S$196.20 (1st yr waived) |
| Citi PremierMiles | 1.2 mpd | 2.2 mpd | Citi Miles never expire; 10,000 renewal miles | S$196.20 (1st yr waived) |
| OCBC 90°N | 1.3 mpd | 2.1 mpd | Up to 7 mpd on Agoda; miles never expire | S$196.20 (1st yr waived) |
| SC Journey | 1.2 mpd | 2.0 mpd | 3 mpd on transport, food delivery and online spend | S$196.20 (1st yr waived) |
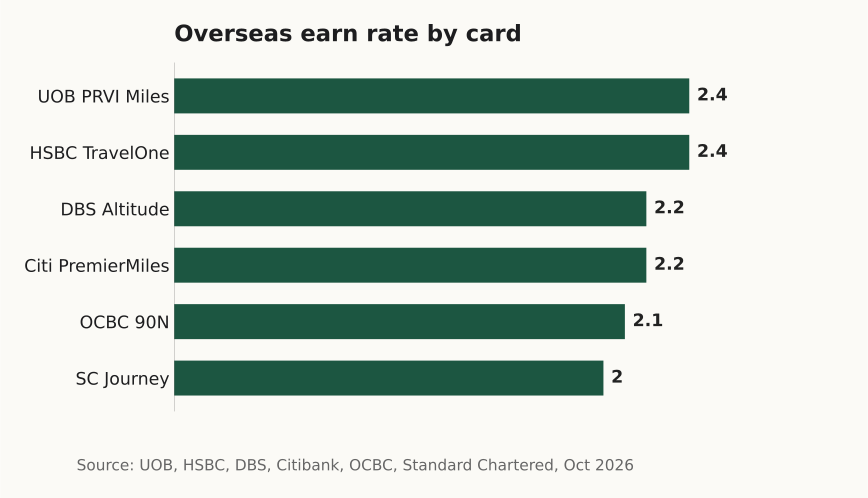
Overseas (foreign-currency) earn rate in miles per S$1, from each bank’s own card page. Bonus categories are additional. Source: UOB, HSBC, DBS, Citibank, OCBC and Standard Chartered, as of Oct 2026.
A few details worth knowing from the banks’ pages: DBS Altitude points, Citi PremierMiles miles and OCBC 90°N miles never expire, which suits slower spenders building up to a redemption. OCBC 90°N, like UOB, awards miles in S$5 blocks rounded down, so small transactions earn less than the sticker rate. Standard Chartered Journey is the odd one out: a lower 1.2/2.0 base, but 3 miles per S$1 on transport, food deliveries and online spend — capped at 3,000 bonus miles a statement cycle.
The fees that quietly eat your miles
The earn rate is only half the story. Before you pick, add up the running costs:
- Conversion/transfer fee: DBS, Citi and Standard Chartered charge about S$25-S$27.25 each time you move points to an airline; UOB charges a conversion fee per transfer; HSBC TravelOne charges nothing for airline or hotel transfers. Frequent, small transfers make this matter.
- Foreign-currency fee: overseas spend carries a fee of roughly 3.25% on most of these cards. On a 2.4 mpd card that fee is the real price of those travel miles — confirm the exact rate on the bank’s page.
- Points expiry: DBS, Citi and OCBC points do not expire; others may, so check before you let a balance sit.
What your miles are worth (illustrative)
Miles have no official price; their value depends on what you redeem for. As a rough guide, a Singapore-dollar spender putting S$3,000 a month (S$36,000 a year) of local spend on a 1.4 mpd card earns about 50,400 miles a year, versus about 43,200 miles on a 1.2 mpd card — a gap of roughly 7,200 miles, enough to matter towards a short-haul economy redemption. Whether that extra is worth S$65 more in annual fee depends on how much you actually spend and whether you redeem for premium cabins (where miles are worth more) or economy (where they are worth less). (Figures illustrative, based on the published earn rates above; actual miles depend on rounding and excluded categories.)
Who should pick what
- Heavy overseas or ASEAN spender: UOB PRVI Miles, for the 2.4 mpd overseas and 3 mpd regional rates — if your spend justifies the S$261.60 fee.
- Wants low fee and painless transfers: HSBC TravelOne — 2.4 mpd overseas, free transfers and lounge access, provided you meet the income rule.
- Books hotels online: OCBC 90°N for up to 7 mpd on Agoda, or UOB for up to 6 mpd via its travel links.
- Spends mostly on transport, food delivery and online: Standard Chartered Journey’s 3 mpd bonus categories.
- Slow accumulator who wants no expiry: DBS Altitude, Citi PremierMiles or OCBC 90°N.
Who should not pick the winner
UOB PRVI Miles is not for everyone. If you cannot comfortably clear the S$50,000 Amex-variant waiver and will pay the full S$261.60 every year, a S$196.20 card may net you more. Its S$5 rounding penalises lots of small charges. And if most of your redemptions are economy short-haul, the higher earn rate buys little extra value over a cheaper card. For pure spending rebates rather than travel, a cashback card is simpler; and if your real goal is growing idle cash, compare high-interest savings accounts instead.
FAQ
What minimum income do I need? Most of these cards ask S$30,000 a year for Singaporeans and PRs (S$40,000-S$45,000 for foreigners); HSBC TravelOne asks S$65,000 unless you hold S$50,000+ with HSBC. Check the card page for your situation.
Is paying the annual fee worth it? Often yes from year two, because DBS, Citi, OCBC and HSBC return 10,000-12,000 bonus miles when you pay it — frequently worth more than the fee. Work out what your miles redeem for before deciding.
Do the miles expire? DBS Points, Citi Miles and OCBC 90°N Miles do not expire; others may. Confirm on the bank’s page if you plan to accumulate slowly.
Can I earn on rent, insurance or taxes? Usually not — these are common exclusions on miles cards. Check each card’s excluded categories.
Related
General information on miles credit cards, not financial advice. Earn rates, fees and waivers change often; confirm the current terms on each bank’s official page before you apply.
Sources
- UOB PRVI Miles Card (earn rates, eligibility and fees) — United Overseas Bank (as of October 2026)
- Terms and Conditions Governing UOB PRVI Miles Card (UNI$ earn and conversion) — United Overseas Bank (as of October 2026)
- HSBC TravelOne Credit Card (miles, lounge access and annual fee) — HSBC Singapore (as of October 2026)
- DBS Altitude Card (earn rates, points validity and fees) — DBS Bank (as of October 2026)
- Citi PremierMiles Card (earn rates, renewal bonus and fee) — Citibank Singapore (as of October 2026)
- OCBC 90N Card (earn rates, S$5 blocks and fee waiver) — OCBC Bank (as of October 2026)
- Standard Chartered Journey Credit Card (bonus categories, cap and fees) — Standard Chartered Singapore (as of October 2026)
- Understanding credit card interest and charges — MoneySense (MAS) (as of October 2026)