CPF LIFE Payouts: How They Work
CPF LIFE is a national annuity that pays a monthly income for life from your Retirement Account savings. For members turning 55 in 2026, the Basic, Full and Enhanced Retirement Sums give estimated payouts of about $950, $1,780 and $3,440 a month from age 65.
CPF LIFE is the scheme that turns your CPF savings into a monthly income that lasts for the rest of your life. It is a national longevity insurance annuity: you pay in a lump sum from your Retirement Account, and in return you receive a payout every month no matter how long you live. This guide explains the three plans, how much the 2026 cohort can expect, when payouts start, and where your money actually goes — with every figure from the CPF Board.
What CPF LIFE is
At 55 a Retirement Account (RA) is created for you, funded from your Special Account and then Ordinary Account savings, up to the Full Retirement Sum. Those RA savings keep earning CPF interest until your payouts begin. When you start payouts, your RA savings are used to buy into CPF LIFE, and the scheme pays you monthly for life. If you outlive your own savings, payouts continue — funded by interest pooled across all members. That pooling is the “insurance” part: it guarantees you never run out of monthly income in old age.
Because the scheme is run by the CPF Board rather than a private insurer, there are no agent commissions or advertising costs baked into it, and the savings are guaranteed by the Singapore Government.
Who is included
You are automatically included in CPF LIFE if you are a Singapore Citizen or Permanent Resident, born in 1958 or after, and have at least $60,000 in your retirement savings when you start your monthly payouts.
If you are a citizen or PR who is not automatically included, you can still enrol voluntarily any time from 65 up to one month before you turn 80. You can also apply to be exempted from CPF LIFE only if you have a pension or private annuity that pays the same or higher monthly payout.
The three plans
CPF LIFE offers three plans. All pay for life; they differ in how the payout changes over time.
| Plan | Monthly payout | Premium deducted | Best for |
|---|---|---|---|
| Standard (default) | Level for life | Entire RA balance at the start | Simple, predictable budgeting |
| Escalating | Starts lower, rises 2% a year for life | Entire RA balance at the start | Keeping pace with rising prices |
| Basic | Starts lower, falls once balances drop below $60,000 | Only about 10-20% of RA at the start | Leaving a larger early bequest |
The Standard Plan pays a steady, level amount; it is the default. The trade-off is that it does not rise with inflation, so you adjust your spending as prices climb. The Escalating Plan starts lower but grows 2% every year for life, which helps your income keep pace with rising costs.
The Basic Plan works differently under the hood. Only about 10-20% of your RA is taken as the premium at the start; your payouts come from the savings left in your RA until one month before you turn 90, and from the premium after that. Its catch is that payouts fall once your combined CPF balances drop below $60,000, because part of the payout is funded by the extra interest CPF pays on your first $60,000. For most people the Standard or Escalating Plan fits better.
When payouts start, and deferring
Your payout eligibility age is 65, but you choose when to actually start — any time between 65 and 70.
If you never choose a plan, you are not left out: with at least $60,000 in your RA, CPF places you on the Standard Plan at 70 and payouts begin then.
How much you will receive
Your payout depends on how much is in your RA, which plan you choose and when you start. The retirement sums are the reference points CPF uses to illustrate this. For members turning 55 in 2026:
| Retirement sum | 2026 amount | Estimated payout from 65 |
|---|---|---|
| Basic Retirement Sum (BRS) | $110,200 | about $950 / month |
| Full Retirement Sum (FRS) | $220,400 | about $1,780 / month |
| Enhanced Retirement Sum (ERS) | $440,800 | about $3,440 / month |
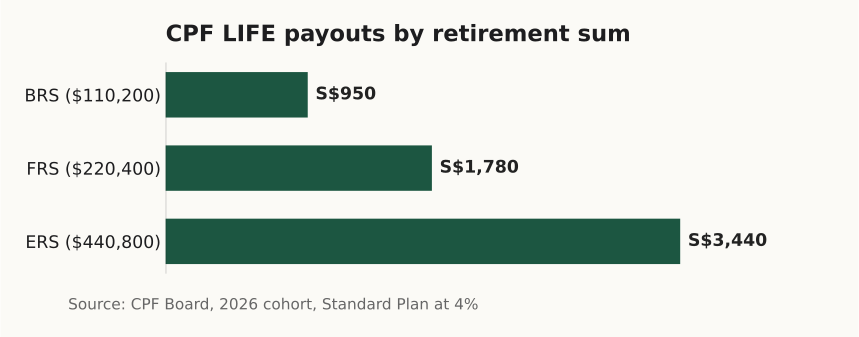
Estimated monthly payouts from age 65 for members turning 55 in 2026, CPF LIFE Standard Plan at 4% interest. Source: CPF Board.
These are CPF estimates for a member turning 55 in 2026, on the Standard Plan, at 4% interest; your own figure will differ. The BRS and FRS are fixed by the year you turn 55 — the 2025 cohort had a BRS of $106,500 and FRS of $213,000, and the 2027 cohort will have $114,100 and $228,200. The ERS rises each year and is the ceiling you can top up to: $440,800 in 2026 and $456,400 in 2027. Since 1 January 2025 the ERS has been set at double the current year’s FRS.
Where your money goes (the premium)
The amount used to join CPF LIFE is called the premium. For the Standard and Escalating Plans, your whole RA balance becomes the premium when payouts start; for the Basic Plan, only about 10-20% does. Either way, your premium keeps earning CPF interest — risk-free returns of up to 6% a year (the 4% floor plus extra interest on your first $60,000 of combined balances) — and that interest is built into your monthly payout, which is why CPF LIFE can pay more than simply drawing down the same lump sum.
Your payouts are drawn first from your own premium. If you live long enough to use it up, payments continue from the pooled interest accumulated across all members — this is the longevity guarantee. And the money is not lost if you die early: your unused premium, plus any remaining CPF savings, goes to your beneficiaries.
How to get a bigger payout
The direct lever is a bigger RA balance before payouts start. You can increase your CPF LIFE premium — and therefore your payout — by making a cash top-up or CPF transfer to your RA, up to the current ERS. If you own a property with a lease lasting until at least age 95, you can meet the FRS with a mix of property (up to half) and cash, freeing some savings. For how top-ups pay off and the tax relief involved, see CPF top-ups: returns and tax relief, and for how the interest that powers these payouts is set, see CPF interest rates explained.
FAQ
Can I change my plan later? You can switch from the older Plus, Balanced, Basic or Income plans to the Escalating or Standard Plan through CPF; check your options before payouts begin, as changes are limited afterwards.
What if I have less than the BRS? You still receive payouts based on whatever is in your RA. With at least $60,000 you get lifelong CPF LIFE payouts; below that, payouts last until your savings run out.
Do payouts ever change after they start? Standard payouts are level; Escalating payouts rise 2% a year. CPF notes that payouts across all plans may be adjusted slightly for long-term changes in interest rates or life expectancy, but such changes are expected to be small and gradual.
Where can I see my own estimated payout? Use the CPF monthly-payout estimator and your Retirement Dashboard after logging in to the CPF website; the figures above are cohort estimates, not your personal amount.
Related
General information on CPF LIFE, not financial advice. Payout figures are CPF Board estimates and change with your balance, plan, start age and interest; confirm your own figures on the CPF website.
Sources
- Receive lifelong monthly payouts with CPF LIFE — Central Provident Fund Board (as of October 2026)
- What is the CPF retirement sum? (2026 sums and estimated payouts) — Central Provident Fund Board (as of October 2026)
- CPF LIFE premiums: how does it work? — Central Provident Fund Board (as of October 2026)
- What is the current Enhanced Retirement Sum? — Central Provident Fund Board (as of October 2026)
- CPF LIFE online brochure (plans and auto-placement at 70) — Central Provident Fund Board (as of October 2026)