CPF Top-Ups: Returns and Tax Relief
A cash top-up to your own or a family member's CPF Special or Retirement Account earns the 4% floor plus any extra interest, and can give up to S$16,000 of income tax relief a year (S$8,000 self, S$8,000 family). SA/RA top-ups count up to the Full Retirement Sum, and the relief sits within the S$80,000 personal relief cap.
Topping up your CPF with cash does two things at once: it adds to savings that earn a guaranteed 4% floor (plus any extra interest), and it can lower your income tax. The scheme is the Retirement Sum Topping-Up (RSTU) scheme, and the relief is the CPF Cash Top-up Relief.
The return
A cash top-up to your Special Account (SA) — or Retirement Account (RA) if you are 55 or older, since the SA was closed for that age group in January 2025 — earns the 4.0% floor rate (for Oct–Dec 2026) plus any extra interest you qualify for on your first balances. That is a risk-free return set by the Government. See CPF interest rates explained for the full rate picture.
The trade-off: top-up money is for retirement, so it is locked for that purpose and cannot be withdrawn like cash in the bank.
The tax relief
Cash top-ups can earn income tax relief:
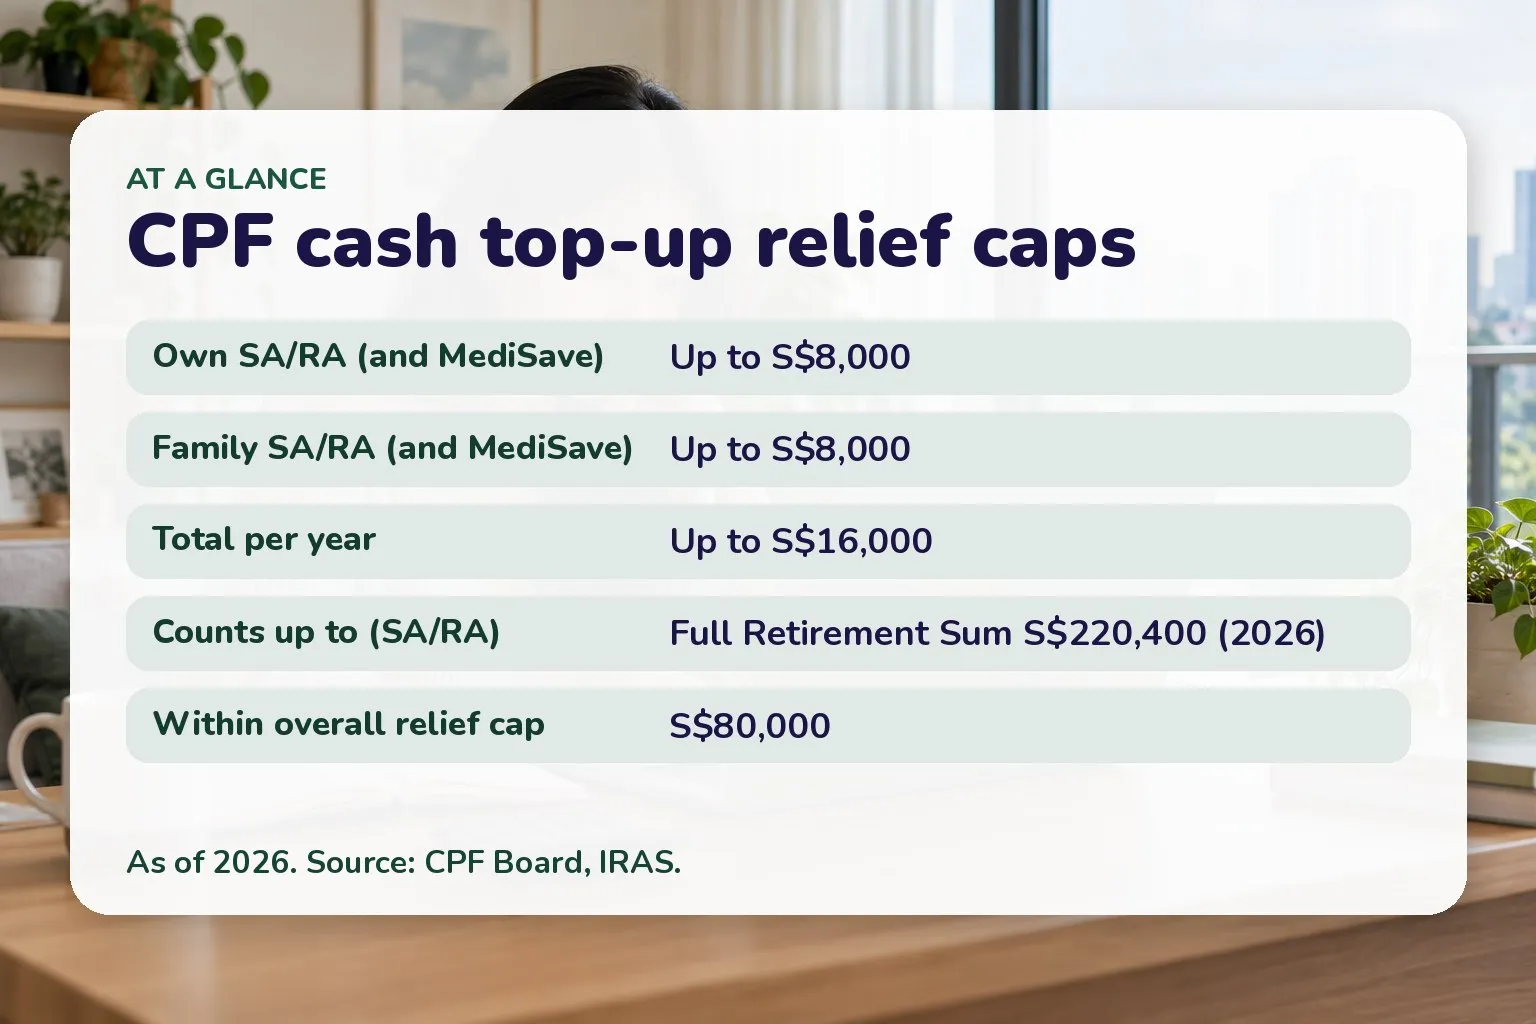
Relief limits for cash top-ups. Source: CPF Board, IRAS.
| Top-up to | Maximum relief per year |
|---|---|
| Your own SA/RA (and MediSave) | S$8,000 |
| Family members’ SA/RA (and MediSave) | S$8,000 |
| Total | S$16,000 |
Two important limits:
- SA/RA top-ups count towards relief only up to the current Full Retirement Sum, which is S$220,400 in 2026. Once the recipient’s balance is at that level, further SA/RA top-ups don’t attract relief.
- The relief sits within the overall S$80,000 personal income tax relief cap. If your other reliefs already approach that cap, a top-up may give little or no extra tax benefit.
Also note: a CPF transfer (moving your own existing CPF savings between accounts) does not qualify for tax relief — only cash top-ups do.
An illustration
This is illustrative. Someone with a marginal income tax rate of, say, 11.5% who tops up S$8,000 to their own RA could reduce tax by about S$920 that year, while the S$8,000 keeps earning the 4% floor plus extra interest inside CPF. The tax saving depends entirely on your own marginal rate and remaining relief headroom.
Who it suits
Top-ups tend to appeal to people who (a) want a guaranteed, CPF-rate return, (b) have taxable income and relief headroom to use, and (c) are comfortable locking the money for retirement. If you need the money accessible, a flexible option like a Singapore Savings Bond or your emergency fund tiers fits better.
Related
General information on CPF top-ups and tax relief, not financial or tax advice. Caps and sums change; confirm the current figures with CPF and IRAS before you act.
Sources
- Top up to enjoy higher retirement payouts (RSTU) — Central Provident Fund Board (as of October 2026)
- CPF Cash Top-up Relief — Inland Revenue Authority of Singapore (as of October 2026)
- Earning CPF interest (4% floor on SA/MA/RA) — Central Provident Fund Board (as of October 2026)