Fixed Deposit Rates in Singapore (October 2026)
As of October 2026 the best broadly available Singapore-dollar fixed deposit rate is about 2.08% p.a., led by finance companies such as Hong Leong Finance. DBS, OCBC and UOB promotions sit lower, near 1.0–1.85%. All need fresh funds.
A fixed deposit (also called a time deposit) locks a lump sum with a bank for a set period in exchange for a rate agreed upfront. In Singapore the gap between the best and worst rates is wide: as of October 2026 the strongest broadly available Singapore-dollar rates are a little above 2% p.a., led by finance companies such as Hong Leong Finance, while the three local banks’ promotions sit lower. Below is who pays what right now, the fine print that quietly lowers your real return, and how an FD stacks up against a T-bill or a high-interest savings account.
Who pays the most right now
For an ordinary saver placing fresh funds, the sharpest mainstream rate as of October 2026 comes from Hong Leong Finance, a licensed finance company, whose 8-month deposit pays 2.08% p.a. on a minimum of S$20,000. Its 12-month promotion reaches 1.90% p.a. for sums of S$100,000 and above (1.80% from S$20,000). The three local banks trail: OCBC’s best online rate is 1.85% for 12 months, UOB tops out at 1.70%, and DBS’s board rate is just 1.00%. Several foreign banks and other finance companies run promotions in a similar band, so it pays to compare a few before committing.
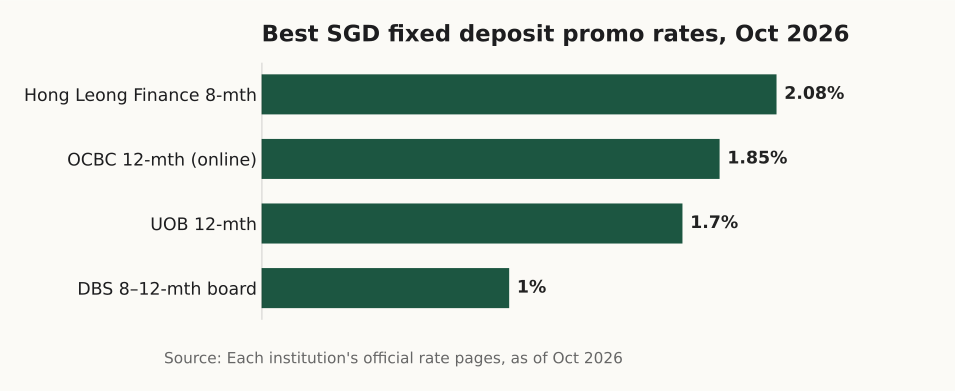
Top advertised Singapore-dollar fixed deposit promo rate at each institution, on fresh funds. Source: each institution’s official pages, as of Oct 2026.
| Institution | Best promo rate & tenor | Minimum (fresh funds) | Notes |
|---|---|---|---|
| Hong Leong Finance | 2.08% p.a. (8-month) | S$20,000 | Finance company; 12-month up to 1.90% (S$100,000+) |
| OCBC | 1.85% p.a. (12-month, online) | S$20,000 | 1.80% at a branch; 1.55% for 6 months |
| UOB | 1.70% p.a. (12-month) | S$10,000 | 1.60% for 6 months, 1.65% for 10 months |
| DBS | 1.00% p.a. (8–12 month board rate) | S$1,000 | Only on S$1,000–S$19,999; 0.05% above that |
The pattern is consistent: the big three local banks pay the least on Singapore dollars because they do not need deposits as hard as smaller and foreign banks and finance companies, which use sharp FD promos to pull in funding. That is why chasing the headline usually means banking somewhere less familiar — and why the rate on your existing bank’s board sheet (DBS pays as little as 0.05% on balances of S$20,000 and above) is almost never the rate to accept.
How a fixed deposit works
You agree to leave a fixed sum untouched for a chosen tenor — commonly 3, 6, 9 or 12 months — and the bank pays the agreed rate, with interest normally paid as a lump sum at maturity. Because the rate is locked when you place the deposit, it does not change if market rates fall during the term, which is the main appeal; the trade-off is that your money is tied up, and you give up the flexibility of a savings account.
Three numbers define any FD offer: the rate (quoted per annum, even for a sub-year tenor), the minimum placement (from S$1,000 at DBS up to S$20,000 for most promos), and the tenor. A per-annum rate on a 6-month deposit earns roughly half that figure in cash: S$20,000 at 2.10% p.a. for a full year is about S$420 of gross interest, but the same rate over six months is about S$210.
The fine print that changes your real return
The advertised rate is rarely the whole story. Three conditions decide what you actually keep.
Fresh funds. Almost every promo applies only to “fresh funds” — money not already held with that bank, or not withdrawn from an existing account there and re-deposited. UOB, OCBC, Maybank and Hong Leong Finance all state this. Money already sitting in your account usually earns only the board rate.
Early withdrawal. Breaking an FD before maturity is costly. UOB states plainly that if a promotional deposit is withdrawn before maturity, no interest is payable; OCBC warns an early-withdrawal fee may apply and you may receive lesser or no interest; DBS says the same. UOB also charges a S$30 early account-closure fee if the account is shut within six months of opening. Only commit money you are sure you can leave for the full term.
Is your money safe
Singapore-dollar fixed deposits are among the safest places to hold cash. Eligible Singapore-dollar deposits — savings, current and fixed deposits — at a Scheme member are insured by the Singapore Deposit Insurance Corporation (SDIC) up to S$100,000 per depositor per member, with all your accounts at that institution aggregated towards the one limit.
For a fuller walkthrough of the scheme, see how SDIC deposit insurance works.
Fixed deposit vs T-bill vs savings account
A fixed deposit is one of three common homes for cash you won’t need for a while, and right now they pay in a similar band:
- T-bill: the latest 6-month Singapore T-bill cut off at 1.95% p.a. (auction 22 October 2026), Government-backed and set by auction rather than fixed by a bank. Yields move every two weeks.
- Fixed deposit: rate locked upfront, insured by SDIC, but interest forfeited if you break it early.
- High-interest savings account: can pay more if your salary credit and card spend tick every bonus box, but the headline evaporates if you miss the conditions — see the savings accounts compared.
An FD wins when you want a guaranteed, hands-off return and can commit the money for the term. A T-bill suits you if you value Government backing and the option to sell in the secondary market; a bonus savings account suits you if your banking habits already clear its hoops.
Using CPF or SRS
You can place a fixed deposit with CPF Ordinary Account savings under the CPF Investment Scheme through an agent bank. OCBC, for example, sets a minimum CPF FD of S$30,000 and notes the first S$20,000 in your CPF-OA cannot be invested; agent-bank transaction and custodian fees also apply. Weigh any CPF FD against the 2.5% p.a. floor the Ordinary Account already pays — if the FD rate is below 2.5%, placing CPF-OA into it makes you worse off. SRS funds can also be placed in some FDs, though several promos (including OCBC’s) exclude SRS.
How to get the best rate
Work through this before placing a deposit:
- Match the tenor to when you need the money. Pick the shortest term that still covers your “won’t touch it” horizon, so you aren’t tempted to break it.
- Check it is fresh funds. If the cash is already with that bank, you may only get the board rate; route it from elsewhere.
- Compare the effective rate, not the headline. Strip out any bundle requirement that parks money at near-zero.
- Confirm the minimum. Most promos need S$10,000–S$20,000; below that your options narrow (DBS takes S$1,000).
- Look beyond your own bank. Finance companies and smaller or foreign banks usually lead the table; all SDIC Scheme members carry the same S$100,000 protection.
- Set the maturity reminder so you re-shop rather than roll over.
Frequently asked questions
What is the best fixed deposit rate in Singapore now? As of October 2026, about 2.08% p.a. for an 8-month deposit from Hong Leong Finance on S$20,000 of fresh funds; the local banks’ best is OCBC at 1.85% for 12 months. Rates change often.
Why do DBS, OCBC and UOB pay less? The big local banks have ample deposits and don’t compete as hard on FD promos; smaller and foreign banks and finance companies use higher rates to attract funds.
What does “fresh funds” mean? Money not already held with that bank (or not just withdrawn from an existing account there and re-deposited). Existing balances usually earn only the board rate.
What happens if I withdraw early? You typically forfeit most or all of the interest, and may pay a fee. UOB pays no interest on a prematurely withdrawn promo deposit; OCBC and DBS may pay lesser or no interest.
Are fixed deposits insured? Yes — eligible Singapore-dollar deposits are covered up to S$100,000 per depositor per Scheme member by SDIC, including deposits with licensed finance companies.
Related
- High-interest savings accounts compared
- Is your money protected? SDIC explained
- How CPF interest rates work
General information on fixed deposit rates, not financial advice. Rates, minimums and conditions change frequently; confirm the current figures on each institution’s official page before you place a deposit.
Sources
- Hong Leong Finance Fixed Deposit promotion (8-month and 6/9/12-month rates) — Hong Leong Finance (as of October 2026)
- OCBC Time Deposit (SGD promotional rates and early-withdrawal terms) — OCBC Bank (as of October 2026)
- UOB Singapore Dollar Time/Fixed Deposit rates (promotion and board rates) — United Overseas Bank (as of October 2026)
- DBS Singapore Dollar Fixed Deposit board rates — DBS Bank (as of October 2026)
- Deposit Insurance Scheme coverage — Singapore Deposit Insurance Corporation (as of October 2026)
- Treasury Bill auction results (listbondsandbills API) — Monetary Authority of Singapore (as of 22 October 2026)
- Earning CPF interest (Ordinary Account floor rate) — Central Provident Fund Board (as of October 2026)