CPF OA and SA: How Interest Stacks
Your CPF Ordinary Account earns 2.5% a year and your Special Account 4%, and an extra 1% on your first $60,000 of combined balances can lift the Special Account to 5%. Moving OA savings to the SA is a one-way, irreversible transfer.
Your CPF Ordinary Account (OA) and Special Account (SA) earn different interest rates and serve different purposes, and the gap between them drives most CPF savings decisions before 55. The OA earns 2.5% a year and the SA 4%, and extra interest on your first balances can push the SA to an effective 5%. This guide explains how those rates stack, how to shift money from the OA to the SA while you still can, and why the once-popular “SA shielding” move no longer does anything.
The rate gap: OA 2.5% vs SA 4%
For 1 October to 31 December 2026, the base rates are 2.5% a year on the OA and 4% on the SA (the same 4% applies to the MediSave and Retirement Accounts). The OA 2.5% is a guaranteed rate; the SA’s 4% is a Government-set floor that has been extended to 31 December 2027 but is not permanent.
Behind the scenes, CPF savings are invested in Special Singapore Government Securities (SSGS) guaranteed by the Government, which is what makes these returns risk-free. For the full detail of how each rate is calculated and reviewed every quarter, see CPF interest rates explained.
How the extra interest stacks
On top of the base rates, the Government pays extra interest on your first balances to boost retirement savings:
- Below 55: an extra 1% a year on the first $60,000 of your combined balances, with the amount counted from the OA capped at $20,000. That lifts the SA’s effective return to as much as 5%.
- 55 and above: an extra 2% on the first $30,000 and 1% on the next $30,000 of combined balances (OA still capped at $20,000).
So two levers decide how hard your CPF works: which account the money sits in (SA beats OA by 1.5 percentage points at the base), and whether it falls inside that first-$60,000 bonus band.
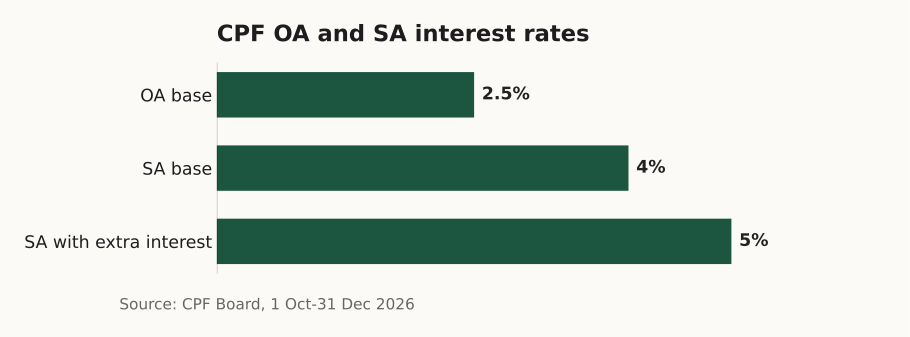
Base rates for Oct–Dec 2026 plus the extra 1% on first balances. Source: CPF Board.
Moving OA savings to the SA
If you are under 55 and sure you will not need some of your OA money for housing, you can transfer it to your SA to earn the higher rate. CPF lets you do this through its online transfer service after logging in with Singpass.
Two rules define the move:
- The cap: before 55, the total you can transfer from OA to SA is limited to the prevailing Full Retirement Sum ($220,400 for a member turning 55 in 2026).
- It is one-way: the transfer is immediate and irreversible. Money moved into the SA cannot come back to the OA.
Before you transfer: the trade-offs
The higher rate is not free of downsides. CPF flags three:
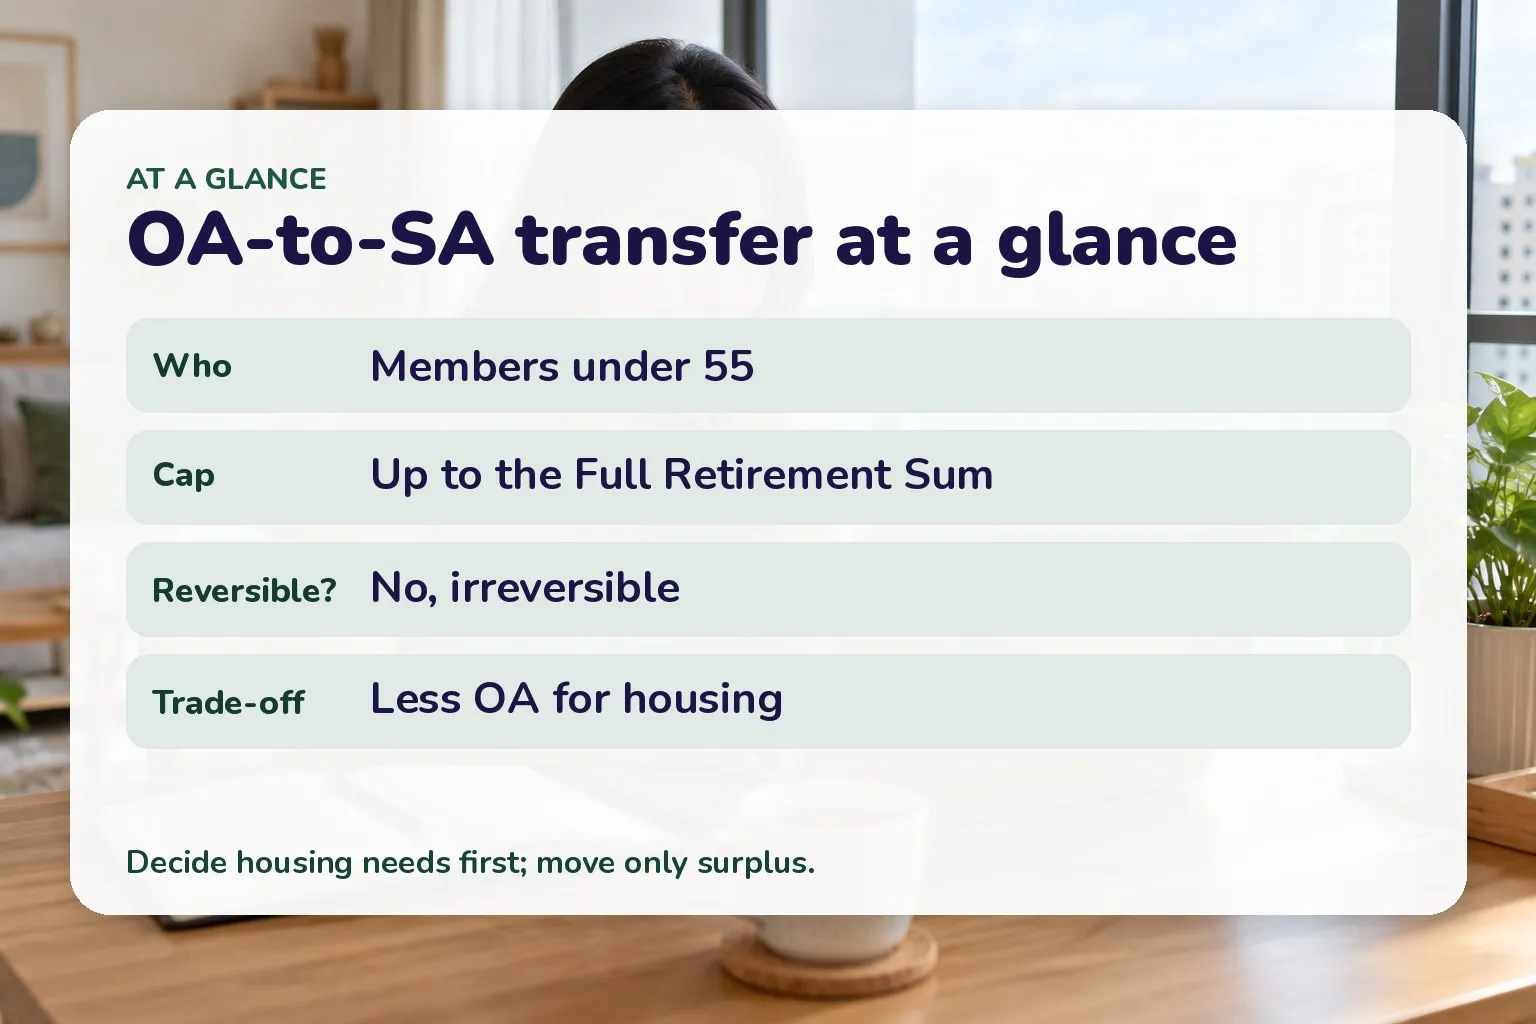
Key rules for transferring CPF savings from the OA to the SA. Source: CPF Board.
- Less for housing. OA savings pay for property and mortgages; moving them to the SA leaves less for a home purchase or monthly instalments, so you may have to top up with cash.
- Possibly less tax relief later. Cash top-ups to the SA earn tax relief only up to the FRS. If a transfer already brings your SA near the FRS, further cash top-ups may no longer qualify for relief.
- No undo. Because the transfer is irreversible, move only what you are confident you will not need before retirement.
Why “SA shielding” no longer works
“SA shielding” was a tactic used just before 55. The idea: when your Retirement Account is created at 55, it is filled from your SA first, then your OA, up to the Full Retirement Sum. By temporarily moving SA cash into an investment just before the birthday, members left less SA cash to be swept into the RA — so the RA drew more from the OA, and the “shielded” SA money kept earning 4% afterwards.
That no longer achieves anything, because there is no Special Account after 55 any more:
So the only way to keep savings earning the 4% long-term rate after 55 is to put them in the Retirement Account, not to try to preserve an SA that no longer exists.
What happens to OA and SA at 55
At 55, a Retirement Account is created and filled from your SA first, then your OA, up to the FRS. After that:
- Savings in the RA earn the 4% long-term floor rate (extended to end-2027).
- Any SA money above the FRS moves to the OA at 2.5%, where you can withdraw it.
- To keep more earning 4%, you can transfer OA savings into the RA, up to the current Enhanced Retirement Sum — again an irreversible transfer, and CPF frames it as a way to earn “higher risk-free returns” instead of taking on investment risk.
FAQ
Is the SA rate guaranteed forever? No. The 4% is a Government-set floor currently extended to 31 December 2027; it is reviewed and extended periodically. The OA’s 2.5% is a legislated minimum.
Does the extra interest apply to every dollar? No — only to your first $60,000 of combined balances (and the OA portion is counted only up to $20,000).
Can I reverse an OA-to-SA transfer if I change my mind? No. CPF states the transfer is immediate and irreversible, so decide carefully.
I’m over 55 — can I still shield my SA? There is no SA to shield; it was closed for your age group. To keep earning the 4% rate, transfer OA savings into your Retirement Account up to the ERS.
Where can I see my own balances and transfer limit? Log in to your CPF account; the transfer service shows the maximum you can move, and the quarterly rates are published on the CPF website.
Related
- CPF interest rates explained
- CPF retirement sums: BRS, FRS and ERS
- CPF top-ups: returns and tax relief
General information on CPF interest and transfers, not financial advice. Rates are reviewed quarterly and transfers are irreversible; confirm the current figures and your own limits on the CPF website.
Sources
- Earning CPF interest (rates and extra interest) — Central Provident Fund Board (as of October 2026)
- 3 simple steps to make a CPF transfer from your OA to SA — Central Provident Fund Board (as of October 2026)
- Closure of Special Account for members aged 55 and above — Central Provident Fund Board (as of October 2026)
- Withdrawing for immediate retirement needs (OA-to-RA transfers) — Central Provident Fund Board (as of October 2026)