CPF Retirement Sums: BRS, FRS and ERS
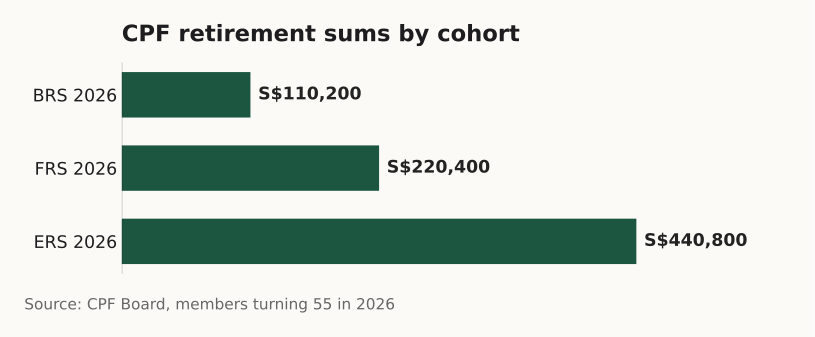
The retirement sum is the savings set aside in your CPF Retirement Account at 55. For members turning 55 in 2026 the Basic sum is $110,200, the Full sum $220,400 and the Enhanced sum $440,800 — the more you keep, the higher your monthly payout.
The CPF retirement sum is the pool of savings set aside in your Retirement Account (RA) when you turn 55 — the money that later funds your monthly payouts for life. CPF gives three reference points for how much to keep: the Basic, Full and Enhanced Retirement Sums. For members turning 55 in 2026 they are $110,200, $220,400 and $440,800. This guide explains what each one is, how much it pays, how the amounts are set, and your options at 55 — every figure from the CPF Board.
What the retirement sum is
The retirement sum is the principal amount of savings in your Retirement Account. The more you keep in the RA, the higher your monthly payout in retirement. It is a target to aim your savings at, not a fee or a hurdle.
One detail trips people up: the sum counts your CPF contributions, top-ups and transfers into the RA, but it excludes government grants and the interest your RA earns. So the interest your savings generate is a bonus on top of the sum, not part of it.
The three reference points
CPF sets three levels so you can match the sum to the lifestyle you want:
- Basic Retirement Sum (BRS) — payouts that cover basic living needs, excluding rent. The entry level.
- Full Retirement Sum (FRS) — exactly double the BRS, and the default amount set aside in your RA at 55.
- Enhanced Retirement Sum (ERS) — double the current year’s FRS (i.e. four times the BRS), and the maximum you can top up your RA to if you are 55 or older. It exists for members who want the highest possible payout.
The 2026 figures (and your cohort)
Here is how the three sums move across recent cohorts. The year is the year you turn 55 — not the current calendar year.
| Turn 55 in | BRS | FRS | ERS |
|---|---|---|---|
| 2025 | $106,500 | $213,000 | $426,000 |
| 2026 | $110,200 | $220,400 | $440,800 |
| 2027 | $114,100 | $228,200 | $456,400 |
Retirement sums by the year you turn 55. Source: CPF Board.
The BRS and FRS are locked to the year you turn 55 and stay the same for the rest of your life, so a member who turns 55 in 2026 keeps a $110,200 BRS even in 2030. The ERS behaves differently: it is the current year’s ceiling, so it rises every January and a member who is already past 55 can top up a little more each year.
What each sum pays you
Your payout depends on how much is in your RA, which CPF LIFE plan you pick and when you start. For a member turning 55 in 2026, on the Standard plan from age 65, CPF estimates:
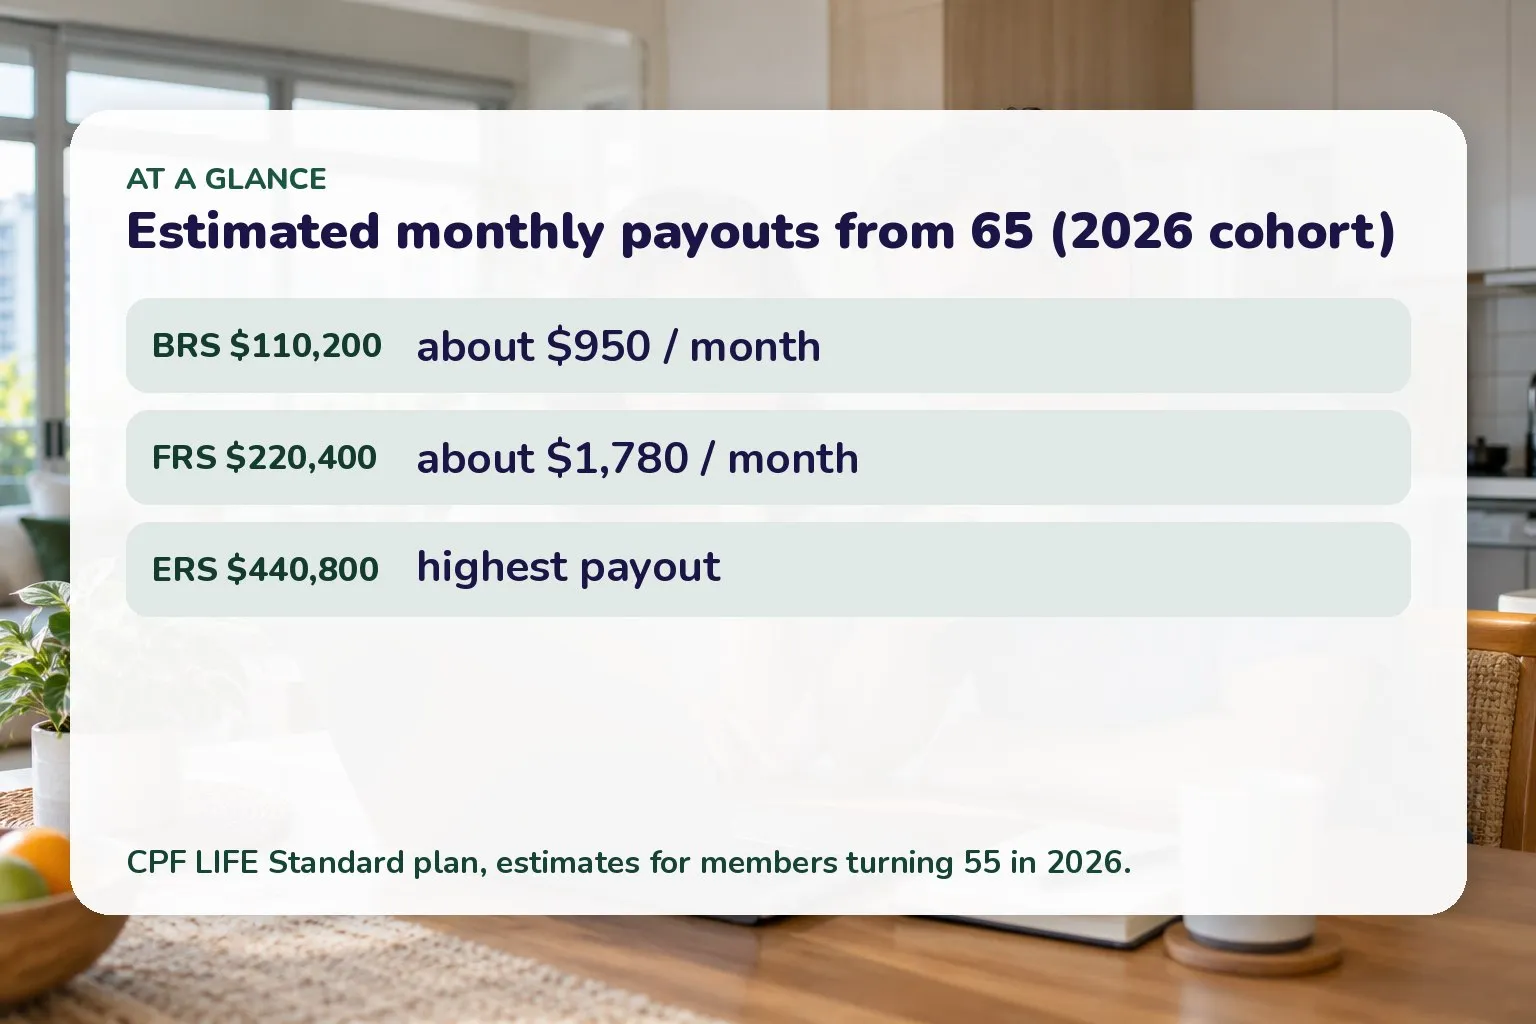
Estimated CPF LIFE monthly payouts from age 65 by retirement sum, 2026 cohort. Source: CPF Board.
| Retirement sum | 2026 amount | Estimated payout from 65 |
|---|---|---|
| Basic (BRS) | $110,200 | about $950 / month |
| Full (FRS) | $220,400 | about $1,780 / month |
| Enhanced (ERS) | $440,800 | higher still (see below) |
As a concrete, dated illustration of the top band: CPF’s own figures for the 2025 cohort show that topping up to that year’s ERS of $426,000 could give payouts of up to $3,300 a month for life from 65. The 2026 ERS is larger, so the payout is higher again; use the CPF payout estimator for your exact number. (Figures are CPF estimates; your own payout will differ.)
For the plans behind these numbers — Standard, Escalating and Basic — see CPF LIFE payouts: how they work.
You do not have to “hit” a sum
Meeting the FRS with a property pledge
You do not have to park the whole Full Retirement Sum in cash. If you own a property in Singapore with a lease that lasts until you are at least 95, you can set aside your FRS with a mix of property and cash — the property can cover up to half of your FRS — and withdraw part of your RA savings in cash, down to the Basic Retirement Sum.
Topping up to the ERS
If you want a bigger payout, you can top up your RA with cash or a CPF transfer, up to the current year’s ERS. Two sweeteners, and one catch, are worth knowing:
- Tax relief: cash top-ups earn tax relief of up to $16,000 a year (combining top-ups to yourself and to loved ones). But relief applies only up to the prevailing FRS — topping up the stretch from the FRS to the ERS boosts your payout without adding tax relief.
- Matched Retirement Savings Scheme (MRSS): eligible members get a dollar-for-dollar government grant, up to $2,000 a year and $20,000 over a lifetime, on top-ups to the RA. From January 2025 the old age cap of 70 was removed. Note that top-ups which attract the MRSS grant no longer get tax relief, because the grant is already the benefit.
What happens at 55
At 55 a Retirement Account is created automatically and filled from your Special Account first, then your Ordinary Account, up to your FRS. From that point:
- If you have met the FRS, you can withdraw the excess savings in your Ordinary Account whenever you like.
- If you have not met the FRS, you can still withdraw $5,000 or more from your CPF savings once you reach 55.
You can make as many withdrawals as you like from your withdrawable savings — there is no need to take everything at once, and leaving it in keeps earning CPF interest. For how that interest is set across your accounts, see CPF interest rates explained.
FAQ
Does my retirement sum change every year? Your BRS and FRS are fixed by the year you turn 55 and stay the same for life. The ERS is the current year’s ceiling and rises each January, so members past 55 can top up a bit more annually.
Is the FRS always double the BRS? Yes. The FRS is set at two times the BRS, and from 2025 the ERS is set at four times the BRS (two times the FRS).
What if I can’t reach the BRS? You still receive payouts on whatever is in your RA. With at least $60,000 in the RA you get lifelong CPF LIFE payouts; below that, payouts last until the savings run out.
Can I top up for someone else? Yes — cash top-ups to a loved one’s RA count towards your combined $16,000 tax-relief cap (up to that person’s FRS), and the recipient may qualify for the MRSS grant.
Where do I see my own sum and top-up room? Log in to your CPF Retirement Dashboard; it shows whether you have met your FRS and how much you can still top up to the ERS.
Related
General information on CPF retirement sums, not financial advice. Payout figures are CPF Board estimates and change with your balance, plan and start age; confirm your own figures on the CPF website.
Sources
- What are the retirement sums (BRS, FRS and ERS)? — Central Provident Fund Board (as of October 2026)
- What is the CPF retirement sum? (2026 sums and estimated payouts) — Central Provident Fund Board (as of October 2026)
- What is the current Enhanced Retirement Sum? — Central Provident Fund Board (as of October 2026)
- Withdrawing for immediate retirement needs (withdrawals from 55, property pledge) — Central Provident Fund Board (as of October 2026)
- Closure of Special Account for members aged 55 and above (ERS top-ups and MRSS) — Central Provident Fund Board (as of October 2026)