Making a CPF Nomination: Why and How
A CPF nomination lets you decide who receives your CPF savings and how much, paid to them in cash. Without one, the Public Trustee's Office distributes your savings under intestacy law, which can take up to six months and costs a fee.
On this page12 sections · tap to jump
- 01Why make a CPF nomination
- 02What a nomination covers
- 03What a nomination does not cover
- 04How your savings are paid out
- 05The three ways to nominate
- 06How to make a nomination
- 07Nominees and witnesses
- 08When to make and review it
- 09What revokes a nomination
- 10Special cases
- 11If you make no nomination
- 12Frequently asked questions
A CPF nomination decides who receives the savings in your CPF accounts when you pass on, and how much each person gets. It takes minutes, costs nothing, and overrides the default rules that would otherwise apply. Without a nomination, your CPF savings are handed to the Public Trustee’s Office (PTO) and distributed under intestacy laws (or the Muslim Inheritance Certificate) — a process that can take up to six months and from which an administrative fee is deducted. This guide explains what a nomination does and does not cover, the three ways to nominate, and exactly how to make one. Every figure and rule here is from the CPF Board.
Why make a CPF nomination
A nomination gives you three things the no-nomination route does not. First, control — you name exactly who receives your savings and in what percentage, rather than letting the law decide. Second, speed — nominees can claim quickly, while the PTO can take up to six months just to identify who is eligible. Third, no cost — making a nomination is free and nominees pay nothing to claim, whereas the PTO deducts an administrative fee before paying out un-nominated savings.
You can make a nomination from the age of 16, and you do not need to be old or unwell to do it. The CPF Board treats it as a basic part of financial planning, alongside knowing your CPF LIFE payouts and your retirement sums.
What a nomination covers
A nomination opens with the direct answer: it covers the cash and balances held inside CPF, but not assets that merely involved CPF money. Specifically, a nomination distributes:
- Savings in your Ordinary, Special, MediSave and Retirement Accounts;
- Your CPF LIFE premium balance (total premiums paid minus payouts already received), if any;
- Your Discounted Singtel shares.
These flow to the people you name, in the shares you set.
What a nomination does not cover
Some things people assume are covered are not. A nomination does not distribute:
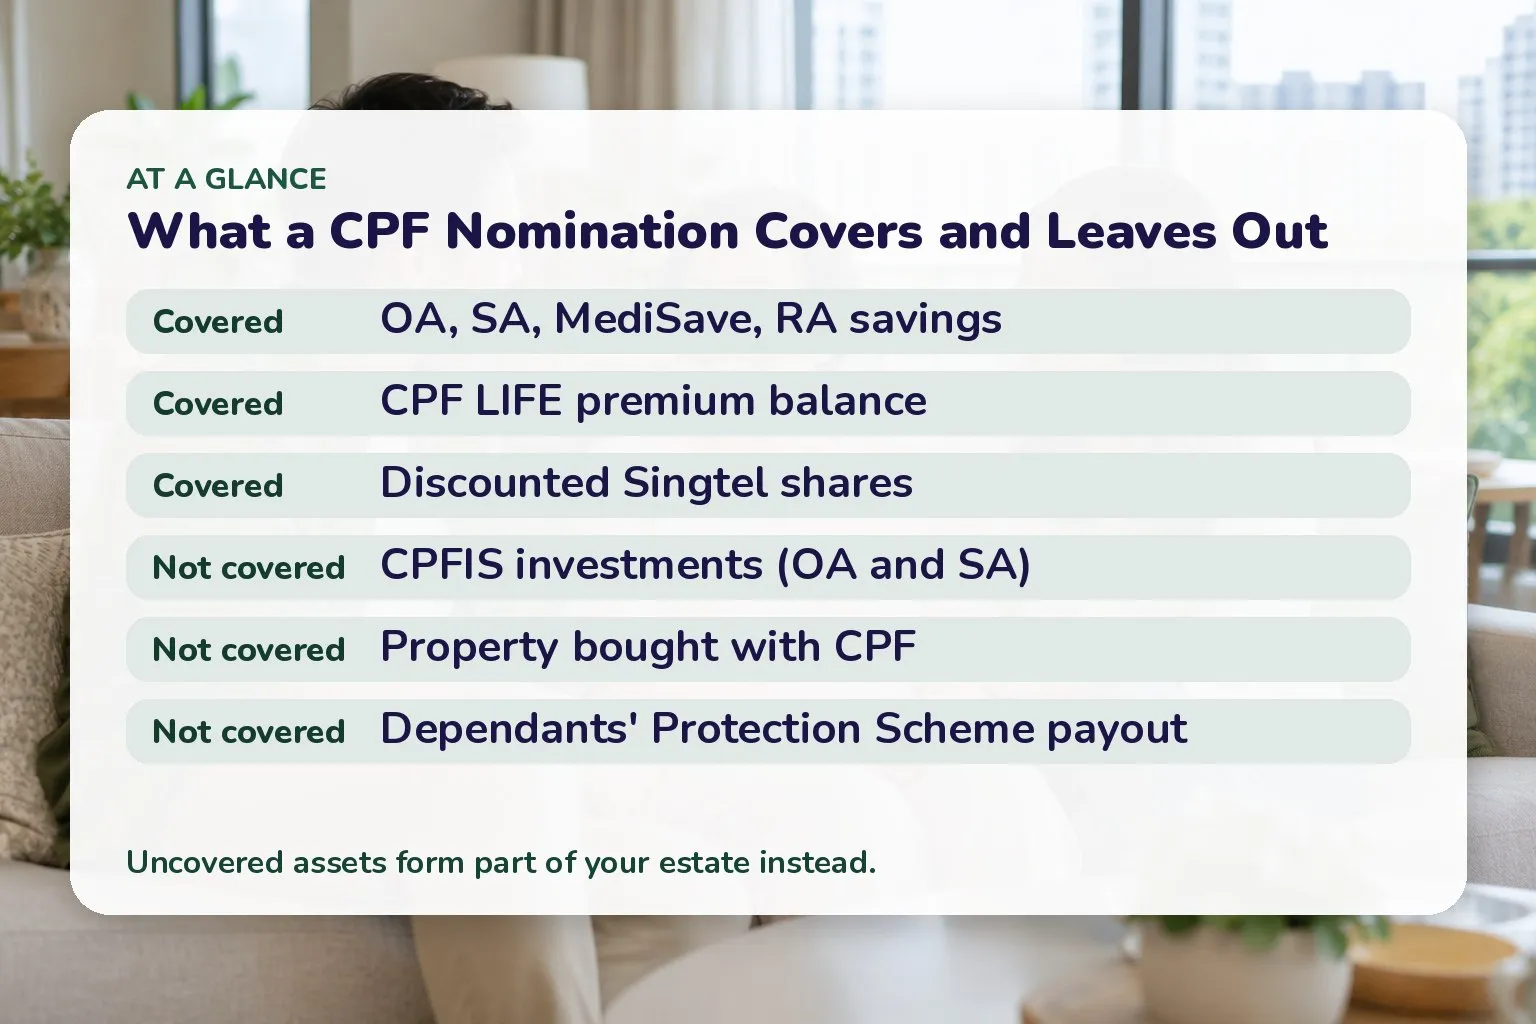
What a CPF nomination does and does not distribute. Source: CPF Board, 2026.
- Property bought with your CPF savings — this is dealt with by how the property is held;
- Dependants’ Protection Scheme (DPS) payouts — these go through your insurer;
- Investments held under the CPF Investment Scheme (CPFIS) — both CPFIS-OA and CPFIS-SA holdings, and the cash in your Investment Account.
The CPFIS holdings and CPF-bought property instead form part of your estate and are distributed through your will or intestacy, not your CPF nomination. If you invest through CPFIS, this gap matters — see our guide to the CPF Investment Scheme for how those holdings are treated.
How your savings are paid out
By default, nominated CPF savings are distributed to your nominees in cash, via PayNow or GIRO. The CPF Board has publicly debunked viral messages claiming the money is instead parked in nominees’ CPF accounts for monthly payouts at 65 — that is not the policy. The Board contacts your nominees within 10 working days of being notified of your death; your family does not need to inform CPF themselves.
If you would rather the money land inside your nominees’ CPF accounts than be paid as cash, you can choose the Enhanced Nomination Scheme instead, covered next.
The three ways to nominate
There is more than one type of nomination, each suiting a different goal.
| Nomination type | What it does | Where to make it |
|---|---|---|
| Standard cash nomination | Pays nominees a lump sum in cash (PayNow/GIRO) | Online or at a Service Centre |
| Enhanced Nomination Scheme (ENS) | Pays the savings into nominees’ own CPF accounts | CPF Service Centre only |
| Special Needs Savings Scheme (SNSS) | Pays a child with special needs a monthly sum | CPF Service Centre only |
The standard cash nomination is the common choice and the only one you can complete online. The Enhanced Nomination Scheme (ENS) suits those who want the money to keep growing at CPF interest rates in a nominee’s own CPF accounts rather than being handed over as cash. The Special Needs Savings Scheme (SNSS) lets a parent set aside CPF savings to be paid to a child with special needs monthly — a minimum of $250 a month for at least a year — instead of a single lump sum, so the funds are not spent too quickly. Both ENS and SNSS must be arranged in person at a CPF Service Centre.
How to make a nomination
For a standard cash nomination you can go online or in person.
Online (the fastest route):
- Log in at cpf.gov.sg with your Singpass and open the make-a-nomination service.
- Add each nominee’s name, NRIC or FIN, mailing address and email, and the percentage share for each.
- Add your two witnesses’ NRIC or FIN, mailing address, email and Singapore-registered mobile number.
- Submit. Your witnesses must acknowledge the nomination within 7 days, or it will not take effect.
You can name up to 8 nominees online; if you want more than eight, you must do it at a Service Centre.
In person:
- Book an appointment at one of the five CPF Service Centres at least one working day ahead.
- Bring your NRIC or passport and photocopies of your nominees’ identification documents.
- Complete the form in front of two witnesses — the CPF customer service officers can act as your witnesses if needed.
Nominees and witnesses
You can name anyone as a nominee — including people who do not have a CPF account. Your two witnesses, however, cannot be your nominees and cannot be an organisation; they are there to attest that you nominated willingly and consciously, which helps prevent disputes later.
When to make and review it
Make a nomination as soon as you start building CPF savings, then revisit it at life milestones: marriage, the birth of a child, divorce, or the death of a nominee. These events change who you would want to provide for, and some of them change your nomination automatically — as the next section explains.
What revokes a nomination
Two rules trip people up:
- Marriage automatically revokes any existing nomination. After you marry, your old nomination is cancelled, so you must make a new one or your savings will default to the PTO.
- Divorce does not revoke a nomination. If you divorce and do nothing, your ex-spouse can remain your nominee — so review it deliberately.
A will still cannot override or substitute for a CPF nomination. And if you marry overseas (a marriage not registered with Singapore’s Registry of Marriages or Registry of Muslim Marriages), notify the CPF Board using its form so the revoke-on-marriage rule is applied correctly.
Special cases
A few situations have their own handling:
- A nominee under 18 when the savings are paid out: that share is held by the PTO until the nominee turns 18.
- A nominee who dies before you: their share is re-distributed to the surviving nominees in the same proportions you set. If no nominee survives, the savings go to the PTO for distribution under intestacy law.
- A nominee who is an undischarged bankrupt at your death: the CPF Board is legally required to inform the Official Assignee.
If you make no nomination
If you never nominate, nothing of your CPF savings is lost — but control is. Your OA, SA, MediSave and RA savings are forwarded to the Public Trustee’s Office, which distributes them in cash under the intestacy laws (or the Muslim Inheritance Certificate). Your family must apply through the PTO, the process can take up to six months, and an administrative fee is deducted. You cannot choose who gets what, and the split follows a fixed legal formula rather than your wishes. For how your CPF money grows while you are alive, see our explainer on CPF interest rates.
Frequently asked questions
Is there any charge to make a nomination? No. Making a CPF nomination is free, and your nominees pay nothing to claim the savings. Only the no-nomination route (via the PTO) carries an administrative fee.
Can I leave my CPF savings in my will instead? No. CPF savings do not form your estate and cannot be distributed by a will. A CPF nomination is the only way to direct them.
Will my nominees get the money in their CPF accounts? Only if you choose the Enhanced Nomination Scheme. By default, savings are paid out in cash by PayNow or GIRO.
I just got married — is my old nomination still valid? No. Marriage automatically revokes any existing nomination, so make a new one after your wedding.
How many people can I nominate? Up to 8 online; for more than eight nominees, make the nomination in person at a CPF Service Centre.
Does my nomination cover my HDB flat bought with CPF? No. Property bought with CPF savings is not covered by a nomination; it is dealt with according to how the property is held.
Related
- CPF LIFE payouts explained
- CPF Investment Scheme (CPFIS) explained
- CPF retirement sums: BRS, FRS and ERS
- CPF interest rates explained
General information on the CPF Nomination Scheme, not financial or legal advice. Rules and schemes are set by the CPF Board and change over time; confirm the current details with the CPF Board before acting.
Sources
- Making a CPF nomination — Central Provident Fund Board (as of November 2026)
- Additional important notes on CPF nomination — Central Provident Fund Board (as of November 2026)
- Your CPF savings will be distributed to your nominee(s) in cash by default — Central Provident Fund Board (as of November 2026)
- CPF answers: what happens to my CPF savings after my death? — Central Provident Fund Board (as of November 2026)
- Special Needs Savings Scheme — Central Provident Fund Board (as of November 2026)