MediSave Uses: What You Can Pay For
MediSave can pay for hospitalisation and day surgery, MediShield Life and approved insurance premiums, selected outpatient care such as chronic-disease treatment, scans and vaccinations, and maternity costs — for you and approved family members, within official withdrawal limits.
On this page9 sections · tap to jump
MediSave is the healthcare pot inside your CPF, built from 8% to 10.5% of your monthly pay. Its uses are wider than most people think: it pays for hospitalisation and surgery, MediShield Life and approved insurance premiums, selected outpatient care such as chronic-disease treatment, scans and vaccinations, and maternity costs — for you and for approved family members. Each use has its own official withdrawal limit, and your balance is capped at the Basic Healthcare Sum. This guide sets out the main MediSave uses and their 2026 limits, with every figure from the CPF Board and the Ministry of Health.
Who you can use MediSave for
You can use MediSave for your own medical bills and for your approved dependants: your spouse, children, parents, grandparents and siblings. Family members can be of any nationality, except grandparents and siblings, who must be Singapore Citizens or Permanent Residents. For some schemes — maternity and assisted conception, for example — you can also tap a spouse’s MediSave.
Hospitalisation and surgery
This is MediSave’s core job: helping with inpatient and day-surgery bills, alongside MediShield Life.
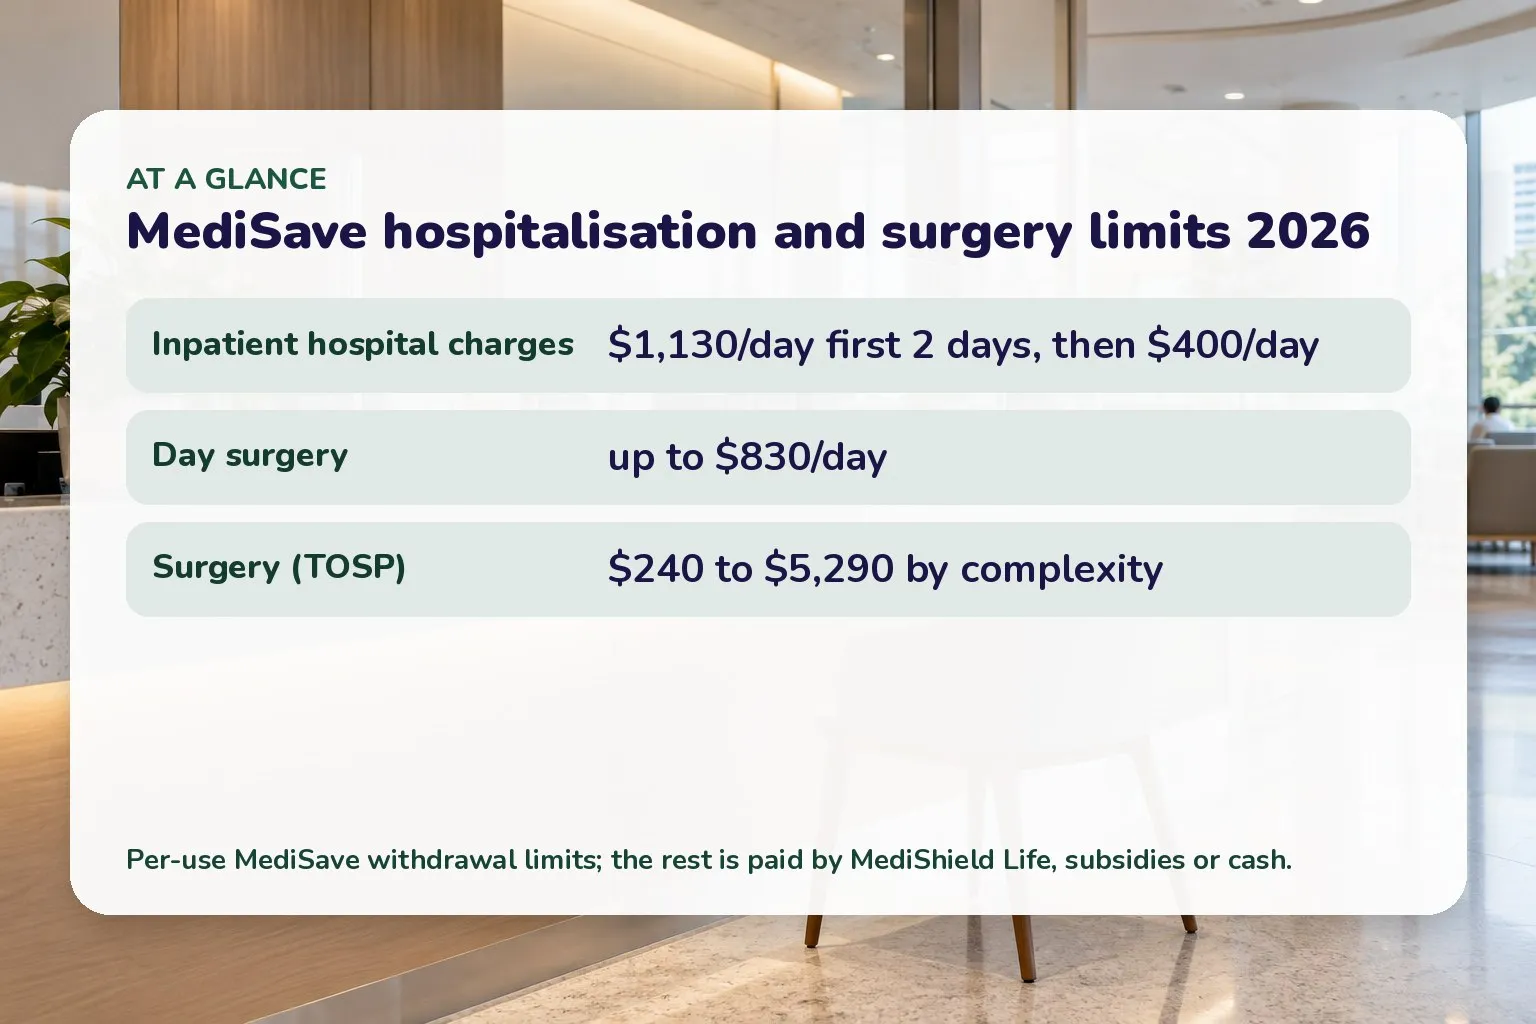
MediSave withdrawal limits for hospitalisation and surgery, 2026. Source: CPF Board.
| Use | MediSave withdrawal limit |
|---|---|
| Inpatient hospital charges | Up to S$1,130/day for the first 2 days, then S$400/day |
| Inpatient psychiatric treatment | Up to S$1,130/day for the first 2 days, then S$230/day |
| Day surgery (hospital charges) | Up to S$830/day |
| Surgery (per the Table of Surgical Procedures) | Between S$240 and S$5,290, by complexity |
The daily limits cover ward charges, treatment fees, investigations and medicines. Surgical withdrawal limits are fixed amounts set by the Table of Surgical Procedures (TOSP), ranging from S$240 for the simplest listed procedures to S$5,290 for the most complex. Anything above these limits is met by MediShield Life (for large bills), government subsidies in subsidised wards, or cash.
Insurance premiums
You can use MediSave to pay the yearly premiums on approved health insurance, including MediShield Life, ElderShield, CareShield Life and the MediShield Life portion of private Integrated Shield Plans. You can fully pay your annual MediShield Life premium from your own MediSave, or a family member’s. MediSave can also pay the MediShield Life outpatient deductible, up to S$500 per policy year. Because premiums recur every year for life, this is one of the most common and valuable MediSave uses.
Outpatient care: MediSave500/700 and more
MediSave is not just for hospital stays. A range of outpatient treatments are claimable, each with its own annual or monthly cap per patient.
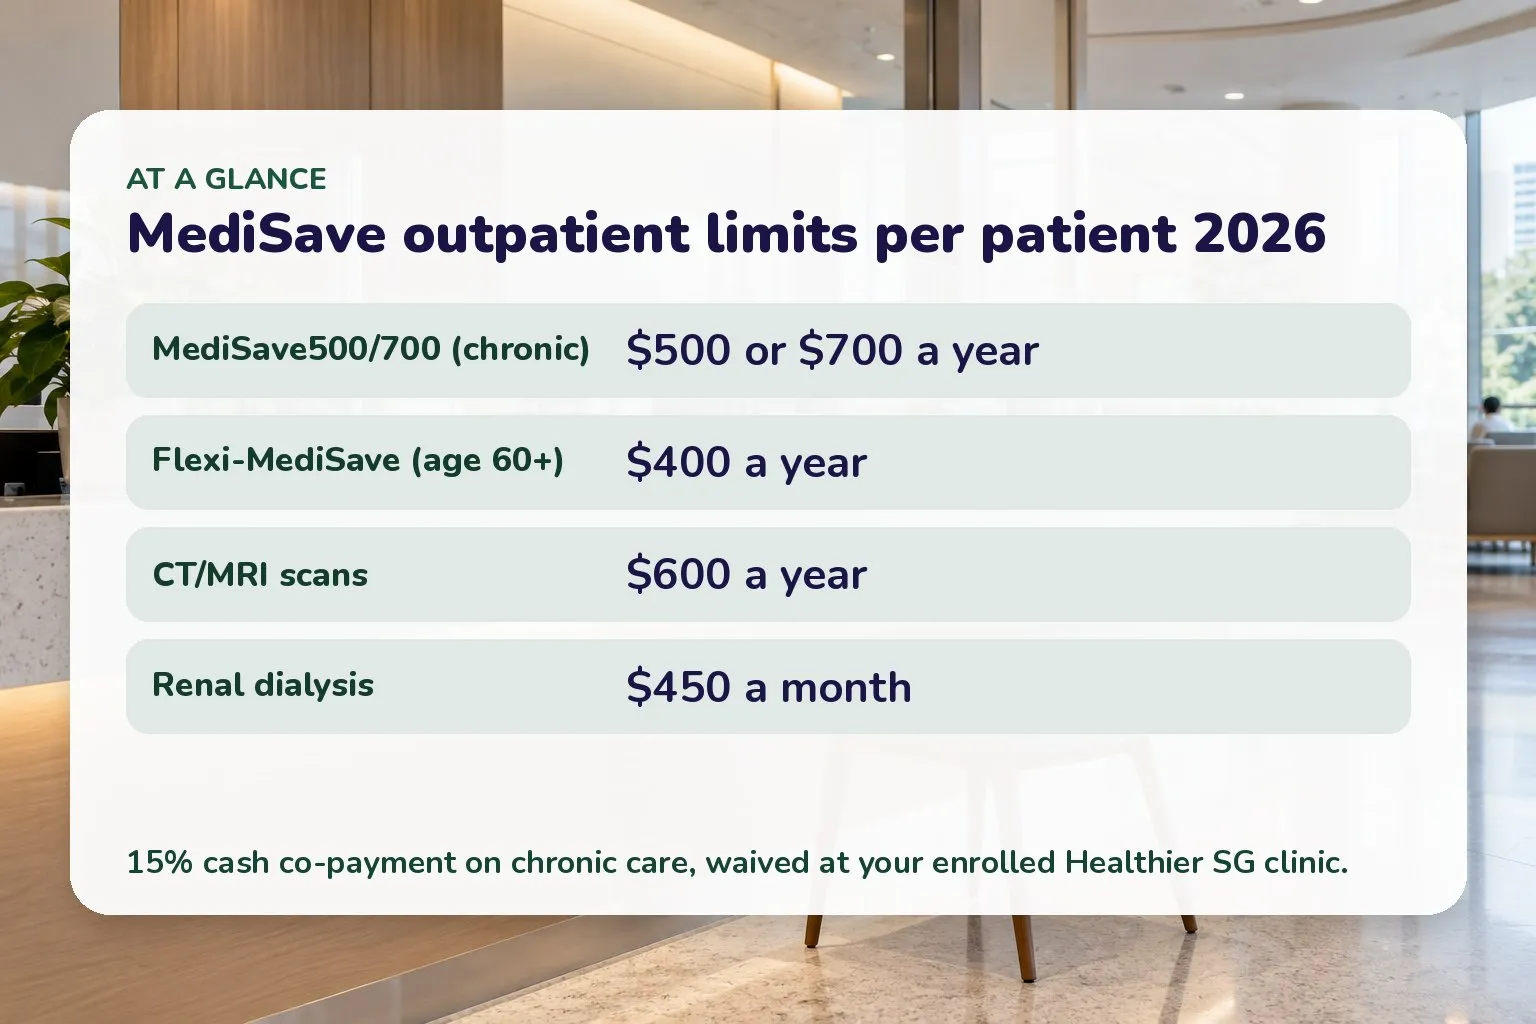
Selected MediSave outpatient withdrawal limits per patient, 2026. Source: CPF Board and Ministry of Health.
| Outpatient use | MediSave limit (per patient) |
|---|---|
| Chronic-disease, vaccinations, screenings (MediSave500/700) | S$500/year (non-complex) or S$700/year (complex chronic) |
| Flexi-MediSave (age 60 and above) | S$400/year |
| CT/MRI scans | S$600/year |
| Renal dialysis | S$450/month |
| Cancer drug treatment (Cancer Drug List) | S$600 or S$1,200/month |
The MediSave500/700 scheme covers outpatient treatment for 23 chronic conditions under the Chronic Disease Management Programme (CDMP) — including diabetes, hypertension, asthma, major depression and others — plus approved vaccinations and health screenings such as mammograms for women aged 40 and above. A 15% cash co-payment normally applies to chronic-disease treatment, except when you are treated at your enrolled Healthier SG clinic, where MediSave can fully pay the bill.
MediSave also covers longer or specialised outpatient treatment — for example anti-retroviral therapy, immuno-suppressants after an organ transplant, and selected high-cost drugs — each under its own monthly limit set by MOH.
Pregnancy and newborns
MediSave supports families through the MediSave Maternity Package (MMP), using your own or your spouse’s MediSave:
- Pre-delivery expenses (consultations, ultrasounds, tests, medications): up to S$900.
- Delivery procedure: up to S$1,120 for a natural delivery, S$2,380 for a caesarean, or S$2,440 for a complicated caesarean.
- Daily hospital charges for the stay: up to S$1,130/day for the first two days, then S$400/day.
Every Singapore Citizen newborn also receives a MediSave Grant for Newborns of S$5,000, credited automatically to a MediSave account opened in the child’s name, to help with premiums, vaccinations and healthcare. Separately, couples can draw on MediSave for Assisted Conception Procedures (such as IVF) at S$6,000, S$5,000 and S$4,000 for the first, second and third-and-subsequent cycles, subject to a lifetime limit of S$15,000 per patient.
Long-term, disability and palliative care
MediSave extends to care beyond the acute hospital. Under MediSave Care, a member aged 30 and above with a severe disability can withdraw up to S$200 a month from their own and/or a spouse’s MediSave, provided at least S$5,000 remains in the account. Rehabilitation has its own daily caps — for example S$250 a day at an approved community hospital. Palliative care is also covered: inpatient hospice care up to S$250 a day (general) or S$350 a day (specialised), while home and day hospice care for a terminally ill patient has no limit from the patient’s own MediSave (a family member’s is capped at S$2,500 per patient per lifetime).
The ceiling on MediSave: the Basic Healthcare Sum
MediSave has a maximum. The Basic Healthcare Sum (BHS) is the most you can hold in the account, and for 2026 it is S$79,000 for members below 65 and for those turning 65 this year. If a MediSave contribution would take you above the BHS, the excess is automatically moved to your other CPF accounts — it is not wasted. Members with less than the BHS can still withdraw from MediSave for approved expenses without topping it up first. Once you turn 65, your BHS is fixed for life. Because MediSave earns the higher CPF interest rate, a full MediSave quietly boosts your retirement balances — see CPF interest rates explained, and how CPF is split across OA, SA and MA for how the MediSave share is set.
How to use or claim
For hospital and day-surgery bills, simply tell the medical institution you want to use MediSave and authorise it; the institution submits the claim to the CPF Board. For maternity pre-delivery costs, pass those bills to the hospital where your baby is delivered. If you have already paid in cash, you can apply to the CPF Board to be reimbursed from MediSave for an eligible expense.
Frequently asked questions
Can I use MediSave for a GP visit? Only for covered outpatient treatments — chronic-disease care under MediSave500/700, approved vaccinations and screenings, or Flexi-MediSave from age 60 at participating CHAS GPs. A routine cold visit outside these schemes is paid in cash.
Can MediSave pay my whole hospital bill? Usually not. Daily and surgical limits cap what MediSave pays; MediShield Life, subsidies and cash cover the rest.
Does MediSave run out? It is not unlimited, but it keeps earning interest and is topped up by contributions while you work. The BHS caps the balance, not your lifetime spending.
Can I use my parent’s MediSave, or they mine? Yes — parents, children and spouses are approved dependants, as are grandparents and siblings who are Singaporean or PR, subject to each scheme’s rules.
What is the 15% co-payment I keep seeing? It is the cash share you pay for chronic-disease treatment under MediSave500/700 — waived if you are seen at your enrolled Healthier SG clinic.
Related
- CPF contribution rates by age
- How CPF is split across OA, SA and MA
- CPF interest rates explained
- CPF retirement sums: BRS, FRS and ERS
General information on MediSave uses, not financial or medical advice. Withdrawal limits and the Basic Healthcare Sum are set by the CPF Board and Ministry of Health and change over time; confirm your own figures with the CPF Board or your hospital before relying on them.
Sources
- Using your MediSave savings — Central Provident Fund Board (as of November 2026)
- Using MediSave for hospitalisation — Central Provident Fund Board (as of November 2026)
- Using MediSave for outpatient treatments — Central Provident Fund Board (as of November 2026)
- Outpatient care (MediSave500/700, Flexi-MediSave) — Ministry of Health (as of November 2026)
- CPF interest rates and Basic Healthcare Sum for 2026 — Central Provident Fund Board (as of November 2026)
- MediShield Life — Central Provident Fund Board (as of November 2026)