CPF Withdrawal at 55: Rules and Limits
From age 55 you can withdraw CPF savings above your Full Retirement Sum from your Ordinary Account, or $5,000 if you have not set the sum aside. There is no limit on the number of withdrawals, and you apply online through your CPF account.
Turning 55 is the first point at which you can take cash out of CPF — but it does not unlock your whole balance. How much you can withdraw depends on one thing: whether you have set aside your Full Retirement Sum in your Retirement Account. This guide covers exactly how much comes out, how to apply, the daily limit, and what changes again at 65. It is the companion to the Retirement Account explained and the retirement sums (BRS, FRS, ERS), which cover how the sums are calculated.
What actually unlocks at 55
At 55 CPF creates your Retirement Account (RA) and moves your Special Account, then your Ordinary Account, into it up to your Full Retirement Sum (FRS). Your Special Account is then closed, and any leftover SA savings move to your Ordinary Account. The money set aside in the RA is reserved to fund your monthly payouts later — so what you can withdraw is essentially whatever is left above the sum.
Only the savings above the FRS, which remain in your Ordinary Account, are withdrawable. If you could not set aside the full sum, a small floor still applies. The amounts and the account structure differ from the SA-to-RA transfer mechanics; here we focus on the cash you can take.
How much you can withdraw at 55
From age 55 to 64 the rule is simple and depends on the FRS:
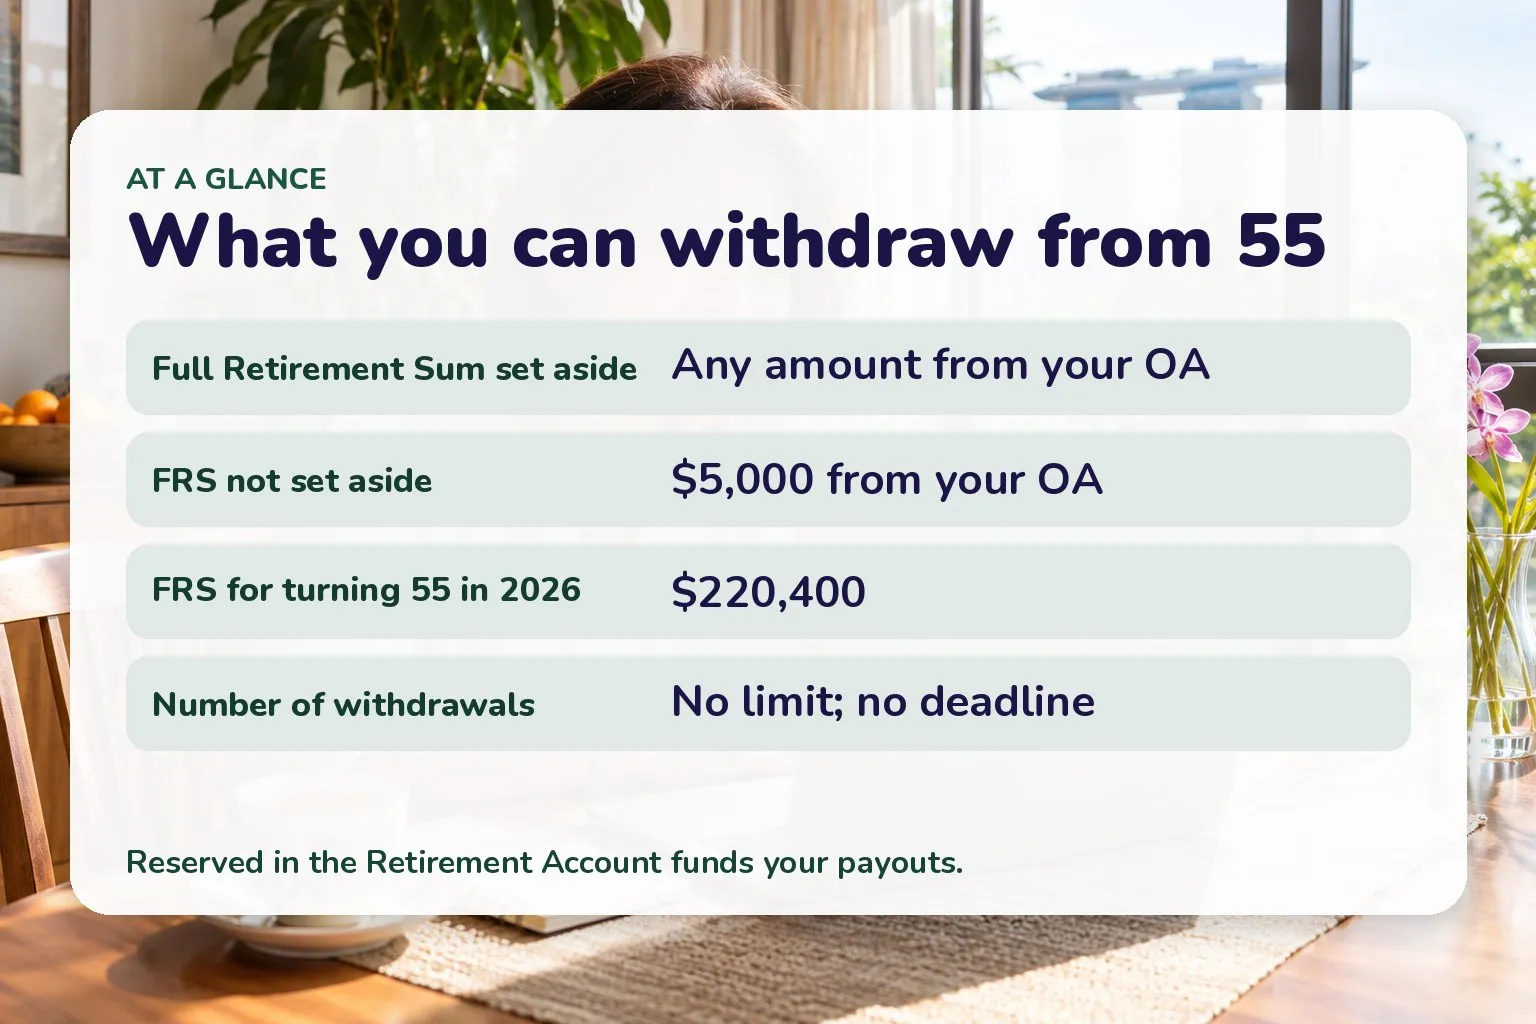
How much you can withdraw at 55. Source: CPF Board, Nov 2026.
- If you have set aside your FRS (in cash, or with a mix of RA savings and property) — you can withdraw any amount from your Ordinary Account.
- If you have not set aside your FRS — you can withdraw $5,000 from your Ordinary Account.
The FRS is fixed by the year you turn 55 and stays the same for life. For members turning 55 in 2026 it is $220,400 (rising to $228,200 for those turning 55 in 2027). You can check your own withdrawable figure any time on your CPF Retirement Dashboard.
Do you have to withdraw anything?
No. Withdrawing is optional and there is no deadline. You can make as many withdrawals as you like from your withdrawable savings, so there is no need to take everything out in one go.
How to withdraw, step by step
Withdrawals are made online through your own CPF account, using the “Withdraw CPF savings for immediate retirement needs” e-service:
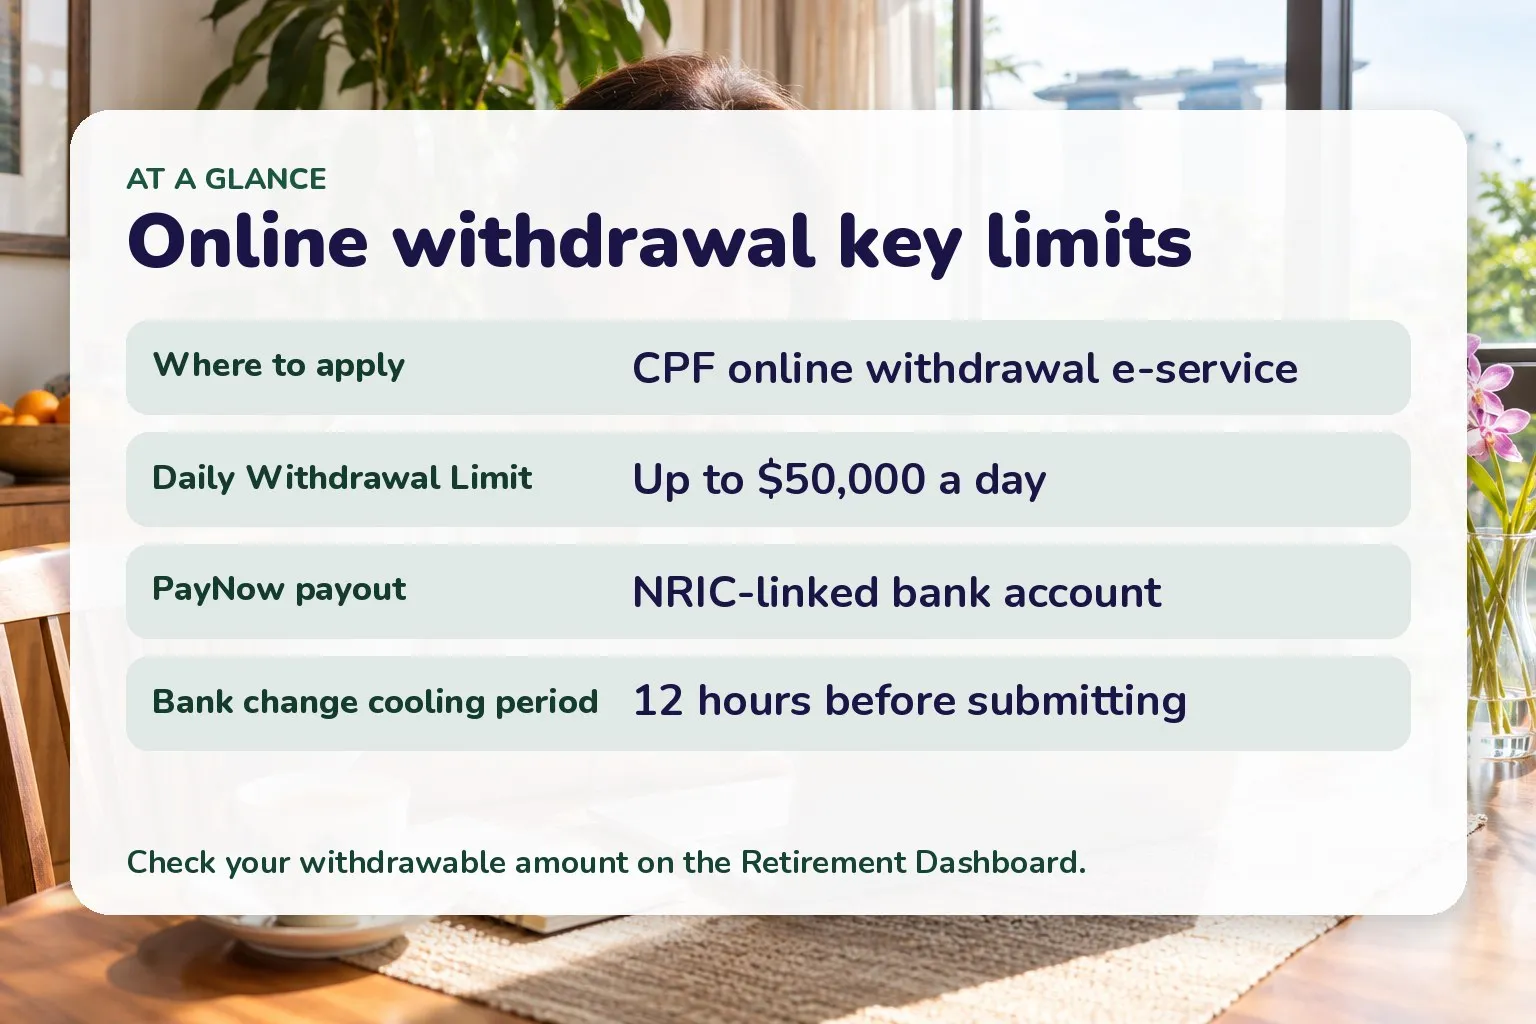
Key limits when withdrawing CPF online. Source: CPF Board, Nov 2026.
- Check your withdrawable amount on your Retirement Dashboard so you know the maximum before you start.
- Update your details first. Make sure your contact details and a bank account are saved in your CPF Account settings. For payment by PayNow, your bank account must be your PayNow NRIC-linked account — set this and wait out the mandatory 12-hour cooling period before submitting, or the application will not go through as expected.
- Log in and submit the withdrawal form, accepting the terms. You may be asked to verify your identity again.
- Stay within the daily limit. Online withdrawals are subject to a Daily Withdrawal Limit, currently a maximum of $50,000 a day; larger amounts are spread across days.
When you have not set aside your FRS and you make a withdrawal, any non-withdrawable amounts left in your Ordinary Account may be transferred into your Retirement Account — so taking the $5,000 can shift the rest toward your payout pot.
Meeting the FRS with property
You do not need the full sum in cash to unlock Ordinary Account withdrawals. You can set aside your FRS with a mixture of RA savings and the CPF you used for your home (a property charge or pledge). That lets you withdraw OA savings above the cash portion while your property counts toward the sum.
What changes at 65
Age 65 is the second milestone. Two things happen:
- Monthly payouts can start. You can begin CPF LIFE payouts any time between 65 and 70; deferring raises your future payout. You are automatically included in CPF LIFE if you are a Singaporean or PR, born in 1958 or later, with at least $60,000 in your Retirement Account when payouts start.
- An additional withdrawal can open. If you are born in 1957 or later, from 65 you may withdraw an additional amount from your Retirement Account savings, depending on your birth year and RA balance (this excludes cash top-ups, CPF transfers and government grants). This is on top of the age-55 Ordinary Account rules: from 65 you can still withdraw any OA amount if the FRS is set aside, or up to $5,000 if not.
A worked example (illustrative)
Frequently asked questions
Can I withdraw my entire CPF at 55? No. Only savings above your Full Retirement Sum (held in your Ordinary Account) are withdrawable, plus a $5,000 floor if you have not set the sum aside. The rest funds your lifelong payouts.
How many times can I withdraw? As many as you like. There is no cap on the number of withdrawals from your withdrawable savings and no deadline to take them.
How soon will I get the money? Withdrawals are made online and paid to your registered bank account, including by PayNow if you have linked your NRIC account. Online withdrawals are limited to a $50,000 maximum per day.
What if I have a serious illness? If an accredited doctor certifies a reduced life expectancy, permanent unfitness for work, or permanent lack of mental capacity, you may withdraw $5,000 or more (excluding Retirement Sum Topping-Up monies and MediSave), though you may still need to set aside a reduced retirement sum for payouts.
Does withdrawing reduce my future payouts? Only money set aside in your Retirement Account funds CPF LIFE. Withdrawing savings above the FRS does not cut your payout; withdrawing the $5,000 floor when you are short of the sum can, since less is set aside. For ways to raise payouts instead, see CPF top-ups: returns and tax relief.
Related
- CPF Retirement Account (RA) explained
- CPF retirement sums: BRS, FRS and ERS
- CPF LIFE payouts: how they work
- CPF interest rates explained
General information on CPF withdrawals at 55, not financial advice. Withdrawal amounts depend on your own balances and cohort; confirm your figures on your CPF Retirement Dashboard before you act.
Sources
- What happens to my CPF savings when I turn 55? — Central Provident Fund Board (as of 4 November 2026)
- Reaching age 55 (withdrawals, property, FRS) — Central Provident Fund Board (as of 4 November 2026)
- How much is my Full Retirement Sum? (2026 sums) — Central Provident Fund Board (as of 4 November 2026)
- Withdrawing for immediate retirement needs — Central Provident Fund Board (as of 4 November 2026)
- What is the Daily Withdrawal Limit for online withdrawals? — Central Provident Fund Board (as of 4 November 2026)
- Withdraw CPF savings for immediate retirement needs (form) — Central Provident Fund Board (as of 4 November 2026)
- Reaching age 65 (payouts and additional RA withdrawal) — Central Provident Fund Board (as of 4 November 2026)
- Withdrawing on reduced life expectancy — Central Provident Fund Board (as of 4 November 2026)